- 01What Changes with the December 2026 Reform
- 02Old vs. New Contribution Caps by Category
- 03How the Cap Works If You Have a Corporate Pension
- 04Enrollment Extended to Under Age 70
- 05Two Routes for Increasing Your Contribution
- 06Steps to Increase Your Contribution
- 07The Once-a-Year Change Rule and Transitional Measures
- 08Why I Kept Mine Unchanged This Time
- 09Keeping the Option to Change Later
- 10Common Pitfalls
- 11Checks Before Considering an Increase
- 12Frequently Asked Questions
- 13Official Sources I Referred To
- 14Summary
Good morning, this is まさきん.
The iDeCo contribution caps are changing significantly starting with the December 2026 contribution. I went back and forth on whether to increase mine, and this time I decided to keep it unchanged. Since the pre-registration deadline is coming up at the end of October, I wanted to write down what I sorted out.
*This information is current as of publication. Please check the official websites for the latest terms.
- Effective December 1, 2026, the cap for employees and public servants is unified at 62,000 yen per month (combined with corporate pensions, etc.)
- Category 1 members such as the self-employed get 75,000 yen per month (combined with the National Pension Fund, etc.), while Category 3 (full-time homemakers) stays at 23,000 yen
- The new caps apply from the December contribution, which means the January 2027 debit
- To increase, you have two options: “pre-registration (e.g., closing October 30)” or “e-iDeCo from December 1 to 24”
- I am keeping mine unchanged for now and plan to look back on it at the end of the year
What Changes with the December 2026 Reform
This reform is part of the pension system reform law passed in 2025. The official iDeCo website says it takes effect on December 1, 2026.
There are two major changes. One is higher contribution limits. The other is a higher maximum age for enrollment.
On the contribution limits, the biggest shift is for company employees. Until now, their cap depended on whether their employer offered a corporate pension. After the reform, it is unified into a single shared limit with corporate pensions.
On top of that, the shared limit is raised to 62,000 yen per month. For the self-employed category, the shared limit with the National Pension Fund becomes 75,000 yen per month.
Honestly, I did not expect the cap for employees to move this much. For someone without a corporate pension, it jumps all the way from 23,000 yen.
Old vs. New Contribution Caps by Category
Based on the official website and plan administrators’ guides, here are the monthly caps for each category.
| Category | Before the reform (through November 2026 contributions) | After the reform (from December 2026 contributions) |
|---|---|---|
| Category 1 (self-employed, freelancers, students, etc.) | 68,000 yen (combined with National Pension Fund, etc.) | 75,000 yen (combined with National Pension Fund, etc.) |
| Category 2: employees without a corporate pension | 23,000 yen | 62,000 yen |
| Category 2: employees with a corporate pension | 20,000 yen (55,000 yen combined with corporate pensions, etc.) | 62,000 yen (combined with corporate pensions, etc.) |
| Category 2: public servants (mutual aid association members) | 20,000 yen (55,000 yen combined with the mutual aid contribution equivalent) | 62,000 yen (combined with the mutual aid contribution equivalent) |
| Category 3 (full-time homemakers, etc.) | 23,000 yen | 23,000 yen (no change) |
| Category 4 (voluntary insured persons) | 68,000 yen (combined with National Pension Fund, etc.) | 75,000 yen (combined with National Pension Fund, etc.) |
| Category 5 (new; age 60 to under 70) | Not applicable | 62,000 yen (combined with corporate pensions, etc.) |
The cap does not change for Category 3. That means they are also not covered by this round of increase procedures.
You can set your contribution from 5,000 yen per month in 1,000-yen increments. That minimum works the same way after the reform.
Laying it out in a table, the expansion of the Category 2 limit really stands out. That said, whether to use it all the way up to the cap is a separate question.
How the Cap Works If You Have a Corporate Pension
If you are an employee with a corporate pension, you need to do a bit of math. You cannot simply put the full 62,000 yen into iDeCo.
According to Ministry of Health, Labour and Welfare materials, your room is 62,000 yen minus the “employer contribution amount.” The employer contribution amount is the total of the following two:
- Employer contributions to a corporate DC plan
- Contribution equivalents of DB and other plans
For example, if your company contributes a total of 20,000 yen per month, your iDeCo room is the remaining 42,000 yen. The bigger the company contribution, the smaller your iDeCo room.
There is one more condition. If you make matching contributions in a corporate DC plan, you cannot join iDeCo. You have to pick one or the other.
I used to build savings in my employer’s corporate DC plan as well. I wrote about how I managed it back then in my post looking back on switching in a corporate DC plan. For anything that overlaps with your company’s plan, checking your employer’s documents first is probably the quickest route.
Enrollment Extended to Under Age 70
The enrollment age is also being raised from under 65 to under 70. This too takes effect on December 1, 2026.
It applies to anyone who falls into one of the following:
- iDeCo members
- iDeCo investment-instruction-only members
- People transferring assets from a corporate pension into iDeCo
In addition, you must not be receiving the old-age basic pension or iDeCo old-age benefits. You are also required not to be making matching contributions.
These people fall into a new category called “Category 5 members.” There is also a transitional measure through the end of November 2029. Under it, people aged 60 to under 70 who do not meet the conditions can newly enroll as well.
If you plan to keep working through your 60s, this reform widens your options. It is still a ways off for me, but it is something I want to remember.
Two Routes for Increasing Your Contribution
If you want to increase from the December contribution, there are two routes. One is “pre-registration” before the effective date, and the other is “e-iDeCo” after it.
Using Rakuten Securities’ guide as an example, it looks like this:
| Item | Pre-registration | e-iDeCo (regular procedure after the effective date) |
|---|---|---|
| Application period | September 1, 2026 to October 30, 5 p.m. (online) | December 1 to December 24, 2026 |
| Paper forms | Must arrive at the company by October 30 | ― |
| Eligible | Category 1, Category 2, and voluntary members who are increasing contributions | Anyone who can use e-iDeCo |
| Takes effect | From the January 2027 debit | From the January 2027 debit |
| What you need beforehand | Logging in to your Rakuten Securities general account | My Number Card and a usage application (account registration) |
Deadlines differ slightly by plan administrator. Monex Securities requires arrival by October 30. MUFG Bank says arrival by October 31.
Rakuten Securities actually recommends doing it through e-iDeCo on or after December 1. The reason is that it can be done online and is less prone to errors.
In other words, even if you miss pre-registration, you are still in time to increase from the December contribution. Learning this took some of the pressure off.
If you are thinking about contributions, it is also worth reviewing fixed costs like your phone bill. It makes it easier to see how much you can set aside each month.
Clicking this opens the Rakuten login page. Once you log in, you’ll see the campaign details.
Steps to Increase Your Contribution
Here is the flow for increasing via e-iDeCo, step by step.
- Check your insured category (Category 1, Category 2, Category 3, etc.)
- If you have a corporate pension, check your company’s contribution amount in your employer’s documents
- Subtract the company contribution from the new cap to calculate your available room
- Get your My Number Card ready and register to use Mynaportal
- Complete the e-iDeCo “usage application (account registration)” in advance
- Between December 1 and 24, 2026, apply to change your contribution amount on e-iDeCo
- Check the January 2027 debit amount to confirm the change took effect
You can complete account registration ahead of time whenever you like. Rakuten Securities notes that applications are concentrated in early December. Apparently registration can take several days to complete.
Also, registration is accepted on weekdays from 8 a.m. to 11 p.m. For mutual aid association members, it is weekdays from 8 a.m. to 9 p.m. The hours are more limited than I expected, so moving early gives you peace of mind.
Avoid applying for the same increase twice through both pre-registration and e-iDeCo. According to Rakuten Securities, if they overlap, both applications become invalid.
The Once-a-Year Change Rule and Transitional Measures
As a rule, you can change your iDeCo contribution amount only once a year. The official iDeCo website describes this as once per year, running from the December contribution through the following November contribution.
However, this reform comes with a transitional measure. According to Rakuten Securities, it covers people on fixed monthly contributions who increase above the pre-reform cap. Such a change is not counted toward the once-a-year limit. This applies through November 30, 2027.
On the other hand, a change to an amount at or below the pre-reform cap counts as one change as usual. For example, an employee going from 10,000 yen to 20,000 yen per month. My understanding is that this change counts toward the limit.
If you pay with monthly designation (annual unit), the treatment is slightly different. If you switch to fixed monthly contributions and at the same time increase above the pre-reform cap, it does not count. If you only switch, it does count.
Honestly, this was the easiest part to misread. If you are unsure, checking your own case in your plan administrator’s FAQ is the safest bet.
Why I Kept Mine Unchanged This Time
This time, I kept my contribution unchanged. I did not use pre-registration either.
When I was torn, the first thing I asked myself was, “Is there any need to rush?” An increase from the December contribution can still be made via e-iDeCo. There is also the option of changing it later than that.
The other thing I thought through was how my income fluctuates from year to year. In a year when you expect a big income, for example, you can change your contribution later through the regular procedure after the reform. The idea is that there is no need to go straight to the cap from the start.
iDeCo contributions are eligible for an income deduction. On the other hand, as a rule you cannot withdraw until age 60. With the limit now wider, I wanted to think carefully about how much to put in.
I plan to review this decision at the end of December. I intend to write again then about whether keeping it unchanged was the right call.
Keeping the Option to Change Later
To me, keeping it unchanged is a little different from “doing nothing.” It is a choice to stay in a position where I can act later.
If you change later, here are the points to keep in mind:
- Complete your e-iDeCo account registration in advance
- Check the application deadline for the year you want to increase in your plan administrator’s guide
- An increase above the pre-reform cap is not counted toward the limit through November 30, 2027
- A change to an amount at or below the pre-reform cap uses your once-a-year change
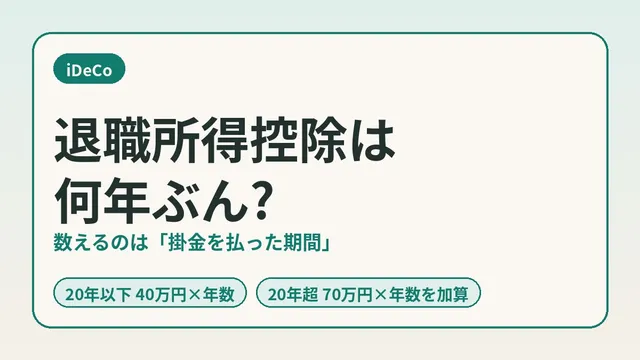
When you think about how you will receive the money at retirement, the length of your contribution period also matters. I covered how the deduction years are counted in my post on iDeCo’s retirement income deduction and enrollment period. Reading it alongside your increase decision may help you see the bigger picture.
Common Pitfalls
Here are some points where people tend to stumble when considering an increase.
- Assuming you can use the full 62,000 yen even though you have a corporate pension
- Applying for the same increase twice through pre-registration and e-iDeCo
- Not noticing that deadlines differ by plan administrator
- Starting e-iDeCo account registration only after December begins
- Thinking you need to file for an increase even though you are Category 3
- Believing you applied and never checking the January debit amount
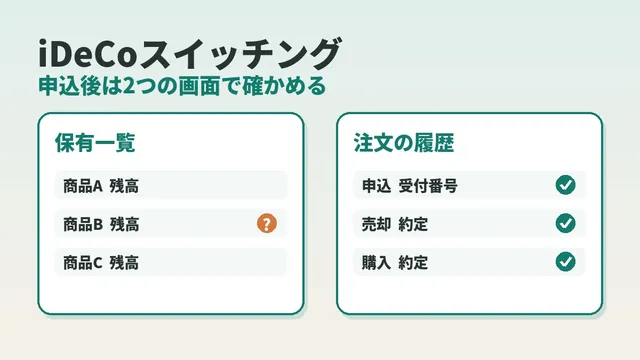
The last point is the same as checking a switch. I explained how to view the records on screen in my post on how to check iDeCo switching. For contribution changes too, confirming it with the record of the debit amount is the safe approach.
Checks Before Considering an Increase
- Which insured category (Category 1 to Category 5) are you in?
- If you have a corporate pension, how much is the company contribution (employer contribution amount)?
- Are you making matching contributions in a corporate DC plan?
- Is your current payment method “fixed monthly” or “monthly designation (annual unit)”?
- When is the pre-registration deadline for your plan administrator?
- Have you completed e-iDeCo account registration and prepared your My Number Card?
Frequently Asked Questions
Q. When can I start using the new cap?
It applies from the December 2026 contribution. The actual debit happens in January 2027. Through the November contribution, the old caps still apply.
Q. If I miss the pre-registration deadline, can I still increase from December?
Yes, you can. According to Rakuten Securities, you apply via e-iDeCo between December 1 and 24, 2026. The change then takes effect from the January 2027 debit. In fact, applying through e-iDeCo is the recommended route.
Q. Do full-time homemakers need to do anything?
The Category 3 cap stays at 23,000 yen per month. So there is no increase procedure needed for this reform. They are also not covered by pre-registration.
Q. What is the cap for employees with a corporate pension?
It is 62,000 yen minus your company’s contribution. The company contribution is the total of employer contributions to a corporate DC plan and the contribution equivalents of DB and other plans. Checking the amount in your employer’s documents is the surest way.
Q. Does the cap go up for public servants too?
Yes, it does. Public servants and other mutual aid association members are in Category 2. Their cap becomes 62,000 yen per month, combined with the mutual aid contribution equivalent.
Q. Does increasing use up my once-a-year change?
If you increase above the pre-reform cap, it is not counted through November 30, 2027. This is the transitional measure described by Rakuten Securities. A change to an amount at or below the pre-reform cap counts as one change as usual.
Q. Will people aged 65 or older be able to join iDeCo?
You will be able to enroll up to under age 70. However, there are conditions, such as not receiving the old-age basic pension. Through the end of November 2029, there is also a transitional measure for people who do not meet the conditions.
Official Sources I Referred To
- Official iDeCo website: About the system reform
- Official iDeCo website: Eligibility, contributions, benefits, etc.
- Ministry of Health, Labour and Welfare: Materials on revising contribution limits (PDF)
- Rakuten Securities: December 2026 reform raising the enrollment age and contribution limits
- Rakuten Securities: iDeCo December 2026 reform and contribution increase information
- Monex Securities: Notice on pre-registration for contribution increases
- MUFG Bank: Pre-registration for iDeCo contribution changes
- SMBC: Explanation of the December 2026 system reform
Summary
This reform greatly widens the contribution cap for company employees. Still, I feel that having more room and using it all right away are two different things.
The pre-registration deadline is close, but December’s e-iDeCo window still works. It seems fine to start without rushing, by checking your category and your company’s contribution.
I will head into the year-end with my contribution unchanged and look back on it at the end of December. Reviewing your fixed costs at the same time may also make it easier to see how much you can set aside.
Clicking this opens the Rakuten login page. Once you log in, you’ll see the campaign details.
This article contains affiliate advertising. If you sign up for a product or service through a link on this site, we may receive compensation from the partner company. The site operator is also an employee of Rakuten Group and may receive compensation through an employee referral program. The content and opinions here are based on the operator’s own experience and research regardless of any advertising relationship, but please read with the above in mind. See the Disclaimer & Affiliate Disclosure for details. Disclaimer & Affiliate Disclosure
This article includes machine-translated content. Please check the official Rakuten Mobile multilingual page for exact terms.
If you have concerns about Rakuten Mobile coverage or signal quality, you can consult through the official signal improvement request form .