- 01The iDeCo retirement income deduction is based on the period you paid contributions
- 02The formula for the retirement income deduction
- 03Quick reference: deduction by number of years
- 04The total enrollment period is a different period
- 05Counting periods when you transferred from a corporate DC
- 06What I found when I checked
- 07Steps to check your participant period
- 08The overlap adjustment when you also receive retirement pay
- 09The change from January 2026
- 10Common mistakes and pitfalls
- 11Fix the assumption before revisiting contributions
- 12Things to confirm before you start
- 13Frequently asked questions
- 14Official sources I referred to
- 15Summary
Good morning, まさきん here.
While revisiting my overall investment plan, I checked how the retirement income deduction (退職所得控除) works when you take iDeCo as a lump sum. The number of years that determines my deduction turned out to be several years shorter than I had assumed. It is easy to mix up which period gets counted, so I am writing down what I found along with how I looked it up.
Note: this information is current as of publication. Please check the official sites for the latest conditions.
- The iDeCo retirement income deduction is determined by the number of months in which contributions were paid (per the official iDeCo site)
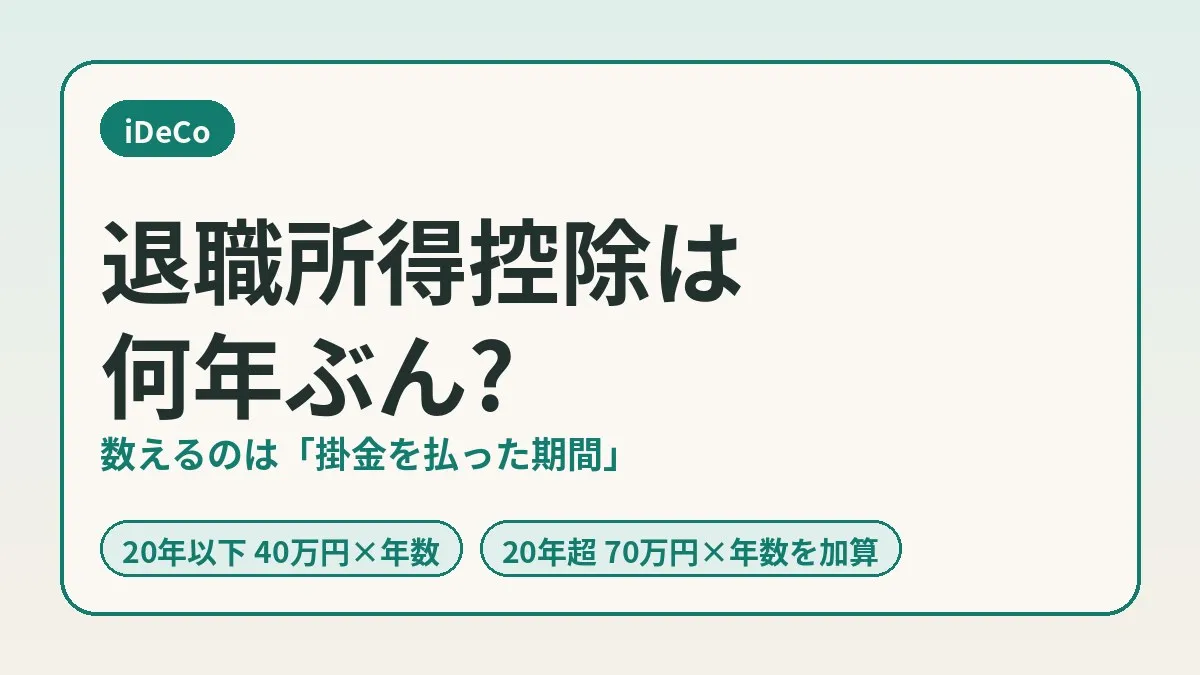
- The formula is 400,000 yen × years for 20 years or less, and 8,000,000 yen + 700,000 yen × (years − 20) for more than 20 years
- Fractions of less than a year are rounded up, and the minimum is 800,000 yen
- The “total enrollment period” (通算加入者等期間) you often see in paperwork is used to set the age at which you can start receiving benefits, and is not the same as the years used for the deduction
- For iDeCo lump sums received on or after January 2026, the window for checking overlap with a later retirement allowance has widened to “within the 9 preceding years”
The iDeCo retirement income deduction is based on the period you paid contributions
iDeCo old-age benefits can be received as a pension or as a lump sum. If you take a lump sum, it is treated as a “retirement allowance” just like severance pay from an employer. That means the retirement income deduction applies.
For ordinary retirement pay, the deduction depends on your years of service. iDeCo has no concept of service. What it uses instead is the period during which you paid contributions.
The FAQ on the official iDeCo site says the deduction “is determined by the number of months in which contributions were paid.” JIS&T, the record-keeping administrator, explains it the same way, wording it as “the contribution payment period is regarded as years of service.”
In other words, it is not the number of years you have held the account. It is the number of years you paid in. I think this is the first fork in the road.
The formula for the retirement income deduction
The formula is published in the National Tax Agency’s Tax Answer No. 1420.
| Years of service (for iDeCo, the contribution period) | Retirement income deduction |
|---|---|
| 20 years or less | 400,000 yen × years (800,000 yen if the result is less than 800,000 yen) |
| More than 20 years | 8,000,000 yen + 700,000 yen × (years − 20) |
At the 20-year mark, the allowance per year changes from 400,000 yen to 700,000 yen. So even a difference of a few years moves the deduction by a fair amount. The closer you are to 20 years, the more the gap tends to show.
According to JIS&T, taxable retirement income is calculated as follows. You subtract the deduction from the old-age lump sum, then halve what is left. If the deduction is larger than the lump sum, no taxable amount arises.
Quick reference: deduction by number of years
Plugging years into the formula gives the following.
| Contribution period (after rounding up) | Calculation | Retirement income deduction |
|---|---|---|
| 2 years or less | Minimum | 800,000 yen |
| 10 years | 400,000 yen × 10 years | 4,000,000 yen |
| 13 years | 400,000 yen × 13 years | 5,200,000 yen |
| 20 years | 400,000 yen × 20 years | 8,000,000 yen |
| 25 years | 8,000,000 yen + 700,000 yen × 5 years | 11,500,000 yen |
| 30 years | 8,000,000 yen + 700,000 yen × 10 years | 15,000,000 yen |
The 13-year row uses the same figures as the example in the official iDeCo FAQ. I calculated the other rows myself by plugging years into the National Tax Agency formula. If you also receive other retirement pay, the adjustment I describe later comes into play.
Fractions of less than a year are rounded up
If the period includes a fraction of less than a year, it is rounded up to one year. In the National Tax Agency’s example, 10 years and 2 months of service becomes 11 years.
The example on the official iDeCo site follows the same idea. If contributions were paid for 150 months, that is 12 years and 6 months. This is rounded up to 13 years, giving 400,000 yen × 13 years = 5,200,000 yen.
So the unit you count in is months. Rather than “roughly what year did I start,” you look at how many months you actually paid a contribution.
The total enrollment period is a different period
I think this is the easiest place to get confused. Defined contribution pensions have two periods with similar names.
| Item | Total enrollment period (通算加入者等期間) | Total contribution period (通算拠出期間) |
|---|---|---|
| What it is used for | Setting the age at which you can receive old-age benefits | The basis for the years used in the retirement income deduction |
| What is counted | Time as a participant plus time as an investment-instruction-only member | The sum of periods in which contributions were paid in |
| Time as an investment-instruction-only member | Included | Not included (no contributions are paid) |
| Corporate DC period | Added in | The participant period in the corporate DC is added in |
| Shown on the annual “Transaction Status Notice” | The period as of the reference date is shown | Could not confirm from official explanations |
I checked the definitions in the glossaries on the official iDeCo site and on the JIS&T site. According to JIS&T, the total contribution period is the sum of your participant periods in corporate DC and iDeCo. For iDeCo, the participant period is described as “limited to the period in which contributions were paid.”
The total enrollment period, on the other hand, also includes time when you had stopped contributing. An investment-instruction-only member (運用指図者) is someone who does not contribute and only gives investment instructions. Because that time is added too, the total enrollment period can end up longer than the period used for the deduction.
The table that sets the benefit start age
For reference, here is what the total enrollment period is actually used for. This table comes from the Ministry of Health, Labour and Welfare’s iDeCo overview page.
| Total enrollment period at age 60 | Age at which you can receive benefits |
|---|---|
| 10 years or more | 60 |
| 8 years or more, less than 10 | 61 |
| 6 years or more, less than 8 | 62 |
| 4 years or more, less than 6 | 63 |
| 2 years or more, less than 4 | 64 |
| 1 month or more, less than 2 years | 65 |
This one is about “when can I start receiving.” It is a separate table from “how much is deducted.” Even if your paperwork confirms 10 years or more, the years for the deduction are not necessarily the same.
Counting periods when you transferred from a corporate DC
If you moved a previous employer’s corporate defined contribution plan into iDeCo, things get one step more complicated.
Under JIS&T’s definition, the corporate DC participant period is added into the total contribution period. When assets are transferred from another retirement benefit scheme, the corresponding period is also added in. So the corporate DC period is not simply thrown away.
However, what gets added is the period in which contributions were paid. It is not the whole time you held an account. For example, periods like the following look likely to cause a gap from what you assumed.
- The time between leaving the corporate DC and starting to pay iDeCo contributions
- Time in iDeCo when you had stopped contributing and were an investment-instruction-only member
- Months when you were a participant but no contribution was paid
These three are my own reading of the official definitions. Which months are actually counted is something you can only know by looking at your own records.
Automatic transfer also needs care. If you do not complete the procedure within 6 months of losing corporate DC eligibility, your assets are automatically moved to the National Pension Fund Association. According to the official iDeCo site, time spent in automatic transfer is not counted toward the total enrollment period. The site notes that the age at which you can receive benefits may be pushed back.
What I found when I checked
In my case too, a transfer from a former employer’s corporate DC is involved. I had been counting my deduction roughly as “from the year I started until now.”
I checked using the participant site of my securities firm and the notices that arrive from JIS&T. The starting point turned out to be different from what I had assumed. The number of years was several years shorter than expected, and the deduction was smaller by that much.
Text extraction from the notice PDF did not work well. I spent a little extra time picking out the numbers. It is something you can just read with your eyes, so simply looking at the screen might have been faster.
I corrected the assumption and recalculated my contributions too. The difference was small, though. So I have left my contribution amount as it is.
What I learned is the order of things: before the amount, check “which period is being counted.” In work terms, I had been comparing numbers without checking the definition of the metric.
I wrote about tidying up what is inside my iDeCo in what I decided before switching out of high-cost funds. The story from my corporate DC days is in my look back at switching within a corporate DC.
For long-running figures like the assumptions behind a payout, checking once keeps paying off. Your monthly phone bill is another fixed cost you can review with the same eye.
Clicking this opens the Rakuten login page. Once you log in, you’ll see the campaign details.
Steps to check your participant period
I think the following order works well.
- Log in to the participant site of your plan administrator (a securities firm, etc.)
- Check whether your status is participant or investment-instruction-only member
- Open the annual “Defined Contribution Pension Transaction Status Notice” (確定拠出年金 お取引状況のお知らせ)
- Confirm that the period shown there is the “total enrollment period”
- Count the months in which you paid contributions from your contribution history
- If you transferred from a corporate DC, ask how the pre-transfer period is treated
- Convert months to years, round up the fraction, and plug it into the formula
For step 2, the JIS&T FAQ shows where to check. It is the screen you reach by opening “Personal registration information inquiry” under “Personal attributes” in the internet service.
Step 6 is the part that is hard to count on your own. I think the most reliable approach is to ask your plan administrator or the record-keeping administrator which period is used for the deduction. The record-keeping administrator is also where claims for old-age benefits are submitted.
What you can see in the Transaction Status Notice
The Transaction Status Notice is a document that reports the valuation of your pension assets and your transaction history. According to JIS&T, sending it at least once a year is required by law.
According to Rakuten Securities, it is issued by JIS&T around late January each year. The reference date is December 31 of the previous year. If you have applied for electronic delivery, you can view the PDF online.
The JIS&T FAQ lists the following 8 items.
- Pension asset status as of the current reference date
- Breakdown of pension asset valuation as of the current reference date
- Breakdown of pension asset valuation as of the previous reference date
- Transaction details
- Amount invested (details of contributions)
- History of changes to allocation by product
- History of benefits
- Total enrollment period as of the current reference date
The last item is the total enrollment period. Rakuten Securities also describes it as the period relating to the eligibility requirements for claiming old-age benefits. Here again, it is not the number of years for the deduction itself.
It seems best not to plug the period shown in the paperwork straight into the deduction formula. What is shown is the period used to set the age at which you can receive benefits. If you had a stretch when you stopped contributing, your years for the deduction may be shorter.
The overlap adjustment when you also receive retirement pay
If you receive both a company retirement allowance and an iDeCo lump sum, there is one more issue. Overlapping periods.
The National Tax Agency’s No. 1420 carries a note. It says that if, for example, you received retirement pay in a previous year, the deduction may be calculated differently. Receiving from two or more sources in the same year is treated the same way.
The detailed conditions are in Tax Answer No. 2732. If there is an overlapping period, an amount equivalent to the deduction calculated on those years is subtracted. For the overlapping period, fractions of less than a year are rounded down.
| Order of receipt | Window for checking overlap |
|---|---|
| Retirement pay first, iDeCo lump sum later | Retirement pay received within the 19 years preceding the year you receive the iDeCo lump sum |
| iDeCo lump sum first, retirement pay later (lump sum on or after January 1, 2026) | Lump sums received within the 9 years preceding the year you receive the retirement pay |
| Between other retirement payments | Retirement pay received within the 4 preceding years |
So anyone whose employment period overlaps with their contribution period needs to watch out. Depending on the timing, you cannot always use both deductions in full.
The change from January 2026
The middle row is what changed in the fiscal 2025 (Reiwa 7) tax reform.
According to the National Tax Agency’s outline of withholding income tax revisions, the content is as follows. Cases where you received an old-age lump sum within the 9 years preceding the year you receive retirement pay other than an old-age lump sum were added to the scope. The old-age lump sums covered are limited to those paid on or after January 1, 2026.
Until then, the window was within the 4 preceding years. Counting the year of receipt as well, 5 years became 10.
Put the other way, old-age lump sums received by December 31, 2025 fall outside the new window. Anyone receiving one from now on will need to plan around the new window.
The tax amount changes with the order and timing of receipt. Individual circumstances matter a great deal here. For a specific tax figure, I think it is best to check with a tax office or a tax accountant.
Common mistakes and pitfalls
Here are the points where I felt it was easy to trip up while researching.
- Using “from the year I opened the account until now” as the number of years
- Assuming the total enrollment period in the paperwork is the number of years for the deduction
- Counting time when contributions were stopped or time as an investment-instruction-only member
- Assuming the whole corporate DC period is added as is
- Remembering the rounding the wrong way around (years are rounded up, overlapping periods are rounded down)
- Adding both deductions together without checking for overlap with retirement pay
- Planning the timing of receipt with the old window, unaware of the January 2026 change
The ones that caught me were around the first and the fourth. I think all of them can be avoided by reading the definitions once.
Fix the assumption before revisiting contributions
The deduction is also an assumption behind how much to contribute. If it is smaller than you thought, your outlook for the lump sum changes too.
That said, fixing the assumption does not always change the conclusion. That was the case for me. The recalculated difference was small, and I left my contribution unchanged.
Even so, I feel checking was worthwhile. I was about to decide how to receive the money on a wrong assumption. Surely you do not have to wait until just before receipt to check?
Things to confirm before you start
- Checked whether my status is participant or investment-instruction-only member
- Counted the months in which contributions were paid, from the history
- Confirmed how the period transferred from a corporate DC is treated
- Noted the total enrollment period in the paperwork and the years for the deduction separately
- Wrote down whether I will get company retirement pay and when I expect to receive it
- Checked the window for the overlap adjustment from January 2026
- Planned on a final check of the tax amount with a tax office or tax accountant
Frequently asked questions
Q. How many years is the iDeCo retirement income deduction calculated on?
It is calculated on the period in which you paid contributions. The official iDeCo FAQ says it “is determined by the number of months in which contributions were paid.” This may not match the number of years you have held the account.
Q. Does time when I stopped contributing count toward the years?
Under JIS&T’s definition, the iDeCo participant period is limited to the period in which contributions were paid. So it reads as though time without contributions does not count toward the years for the deduction. The total enrollment period, which sets the benefit start age, does include time as an investment-instruction-only member.
Q. Is the corporate DC period added in?
Under JIS&T’s definition, the total contribution period is the sum of the participant periods in corporate DC and iDeCo. So yes, it is included. However, which months are counted differs from person to person. If you transferred, asking is the surest way to find out.
Q. Where can I check my participant period?
The annual “Defined Contribution Pension Transaction Status Notice” shows your total enrollment period. However, that is the period for the benefit start age. For the period used in the deduction, it seems best to check your contribution history or ask your plan administrator.
Q. What happens to fractions of less than a year?
Fractions in the number of years are rounded up to one year. In the official iDeCo example, 150 months is calculated as 13 years. On the other hand, fractions in the period overlapping with retirement pay are rounded down.
Q. Can I use the deduction for both retirement pay and the iDeCo lump sum?
If the periods overlap and the timing of receipt falls within a certain window, an adjustment applies. The deduction for the overlapping years is subtracted. The window depends on the order of receipt, so take a look at the National Tax Agency’s No. 2732.
Q. What changed from 2026?
The window widened for cases where you receive the iDeCo lump sum first and retirement pay later. It went from within the 4 preceding years to within the 9 preceding years. This applies to old-age lump sums received on or after January 1, 2026.
Q. Where should I confirm my own tax amount?
This article sorts out how the system works. It does not go as far as individual tax amounts. The result changes with how and when you receive the money, so please check with a tax office or a tax accountant.
Official sources I referred to
- No. 1420 When you receive retirement pay (retirement income) | National Tax Agency
- No. 2732 Withholding tax on retirement allowances | National Tax Agency
- Outline of withholding income tax revisions: details of the tax reform (PDF) | National Tax Agency
- Frequently asked questions | Official iDeCo site
- Glossary | Official iDeCo site
- For those who have changed jobs or retired | Official iDeCo site
- Overview of iDeCo | Ministry of Health, Labour and Welfare
- For those receiving benefits | JIS&T
- Total enrollment period | JIS&T glossary
- Total contribution period | JIS&T glossary
- How do I read the Transaction Status Notice? | JIS&T
- How do I check my participant category? | JIS&T
- How to read the Transaction Status Notice | Rakuten Securities iDeCo
Summary
The iDeCo retirement income deduction is determined by the period in which you paid contributions. It turned out to be a different period from the total enrollment period shown in the paperwork. If you transferred from a corporate DC, it is worth looking at how the periods are combined as well.
When I checked, I found my deduction was smaller than I had assumed. I have not changed my contributions. But with the assumption now correct, I think I have a foundation for thinking about how to receive the money.
What I have written here is a summary of the system and a record of my own check. It is not tax advice. Why not start by counting the months you paid contributions in your history?
The habit of checking assumptions carries straight over to monthly fixed costs. Your phone bill may be worth a look too, for peace of mind.
Clicking this opens the Rakuten login page. Once you log in, you’ll see the campaign details.
This article contains affiliate advertising. If you sign up for a product or service through a link on this site, we may receive compensation from the partner company. The site operator is also an employee of Rakuten Group and may receive compensation through an employee referral program. The content and opinions here are based on the operator’s own experience and research regardless of any advertising relationship, but please read with the above in mind. See the Disclaimer & Affiliate Disclosure for details. Disclaimer & Affiliate Disclosure
This article includes machine-translated content. Please check the official Rakuten Mobile multilingual page for exact terms.
If you have concerns about Rakuten Mobile coverage or signal quality, you can consult through the official signal improvement request form .